More than 10 million potential credits sit in a single queue. That is the scale of the 23 Vietnamese projects that have received approval letters from the Ministry of Agriculture and Environment to move into the United Nations mechanism under Article 6.4 of the Paris Agreement, covering reductions from 2021 to 2025. Set beside the 1,310 allowances traded in the first months of Vietnam’s domestic carbon exchange, the queue shows where future supply could come from, and why forests and rice fields matter more to that story than factories do.
This article compares the three supply lanes now forming: bilateral deals under Article 6.2, the United Nations route under Article 6.4, and domestic standards issued by Vietnamese authorities. Each lane has a different buyer, a different timetable and a different price signal. Together they will decide whether Vietnam becomes a regular exporter of verified reductions or a country with a long list of promising projects that never quite reach issuance.
Lane one: bilateral deals with named buyers
Article 6.2 covers cooperation agreed directly between governments. Vietnam has launched cooperation with Singapore and Japan, and joint committee meetings with both partners are scheduled in the coming period, according to CarbonMeld reporting in September 2026 and the ministry briefing it draws on. The earliest projects under these mechanisms are expected to launch in December 2026.
The Singapore track already has legal form. Vietnam’s government approved the implementation agreement on carbon credit collaboration with Singapore in August 2026, under a pact signed in September 2025. Reporting on that approval describes a binding framework under which Vietnamese organizations can develop projects, generate credits to international standards, and transfer them to Singapore once eligible methodologies are published.
South Korea and Switzerland sit one step behind. Vietnamese officials have said technical negotiations with both are being promoted, with signing expected by the end of 2026. That sequencing matters for developers, because a bilateral agreement defines which project types a buyer country will accept, how corresponding adjustments are handled, and what documentation an exporter must produce before a single credit can move.
Lane two: the United Nations queue
The Article 6.4 lane is larger and slower. The 23 approved projects still need to complete the remaining United Nations requirements before formal registration and issuance. CarbonMeld notes that officials expect a relatively large new source of supply once that happens, but no firm issuance date has been published.
Scale cuts both ways. A pipeline above 10 million credits would dwarf early domestic trading, yet credits covering 2021 to 2025 reductions arrive into a market whose buyers care about vintage, methodology and delivery risk.
Lane three: domestic standards for forests and rice
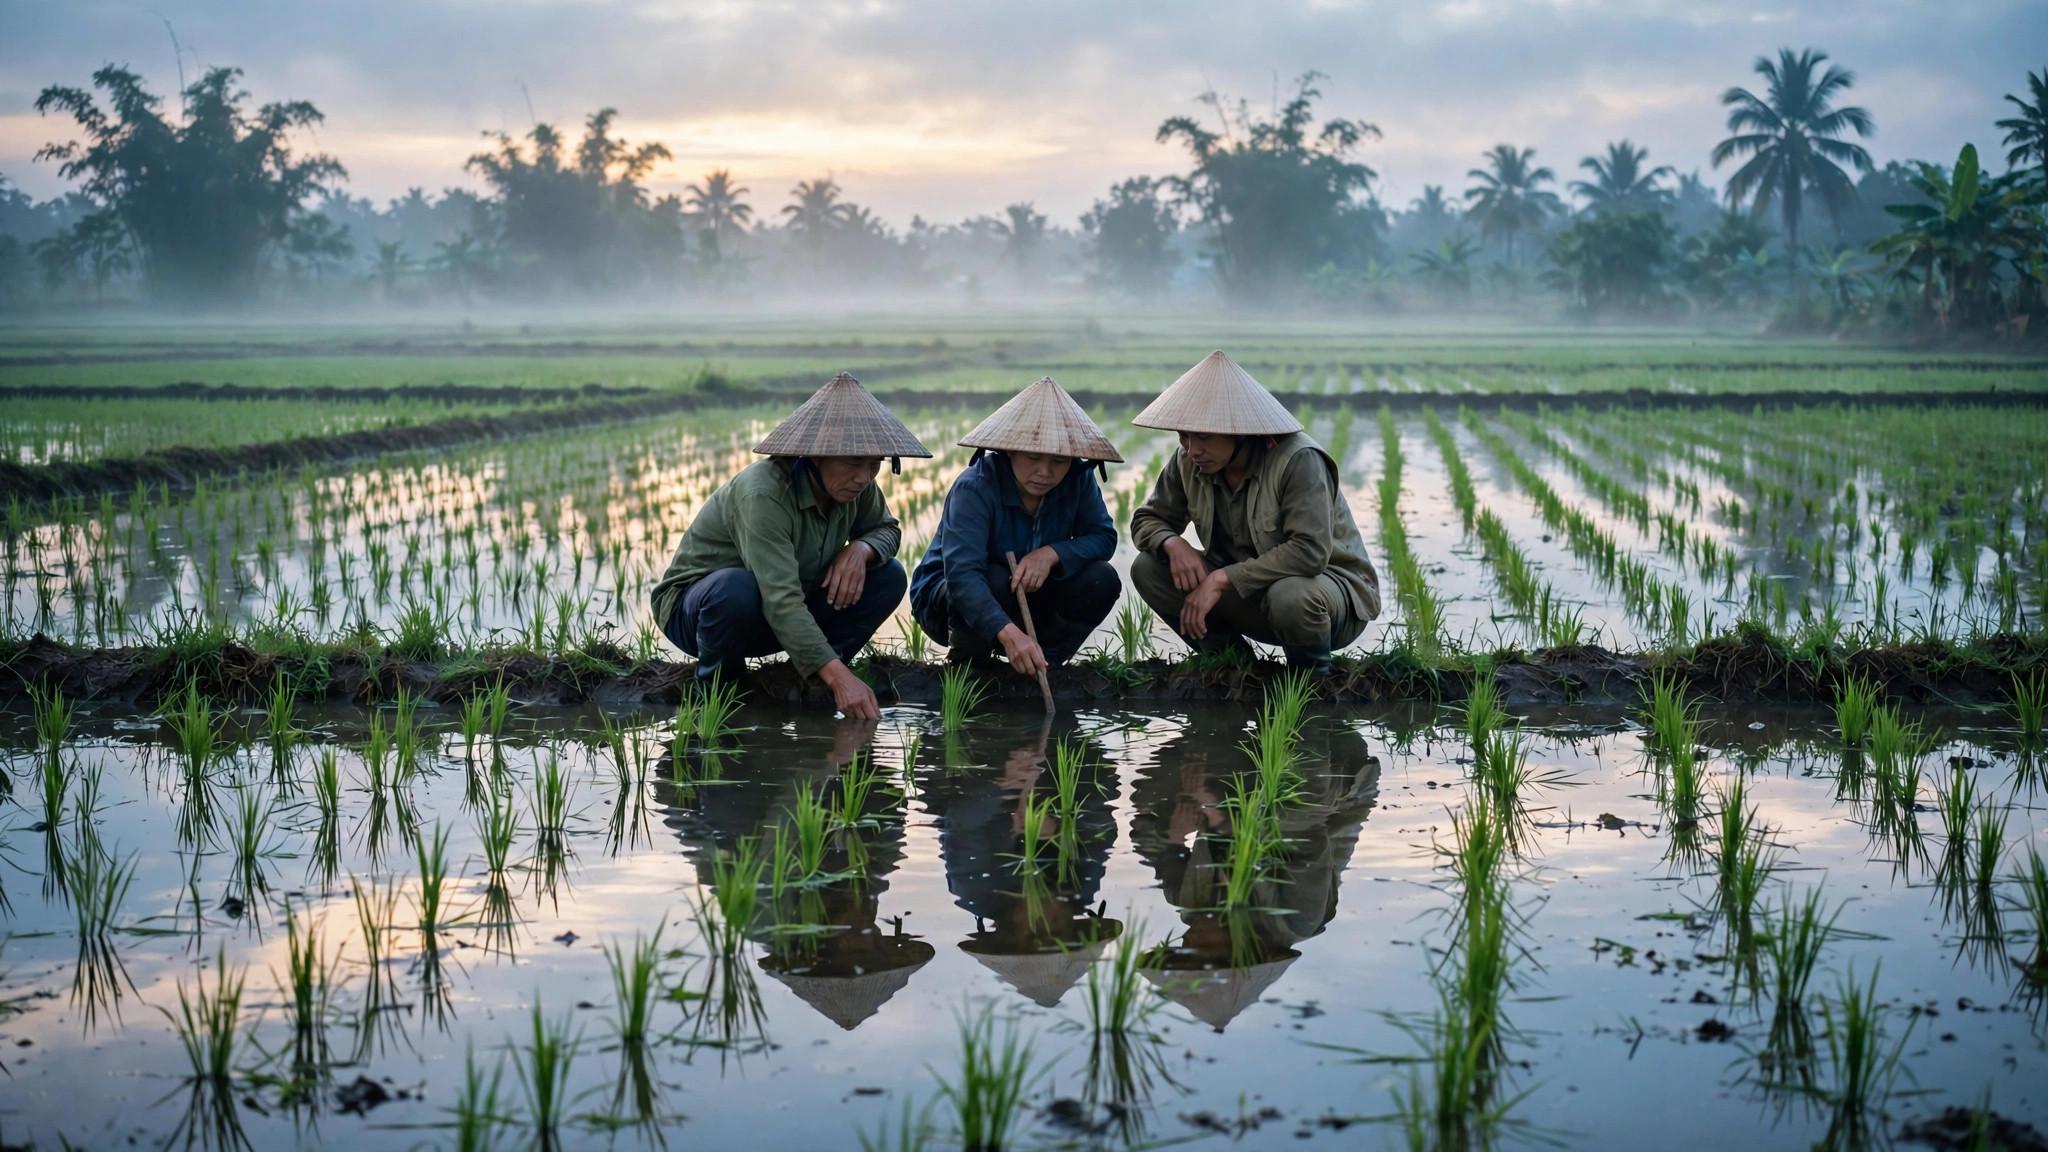
The third lane is home grown. Vietnam issued its forest carbon credit standard on August 11, 2026, and the climate department expects forest projects certified under it to supply the domestic exchange in future. The flagship one million hectare high quality, low emission rice program in the Mekong Delta would also be eligible for listing if its credits are developed through bilateral cooperation or the United Nations standard.
Forests bring proof of concept. Under the World Bank Forest Carbon Partnership Facility agreement signed in 2020, Vietnam transferred 10.3 million tonnes of carbon dioxide reductions from six north central provinces and earned USD 51.5 million, at about USD 5 per tonne, with more than 70 percent of the payment directed to forest owners, communities and local managers. That deal predates Article 6 trading, but it demonstrates the measurement and benefit sharing machinery that forest credits need at scale.
Rice brings volume and a different price talk. Vietnam Investment Review reported in 2026 that a low emission rice project using alternate wetting and drying across about 80,000 hectares in 15 provinces expects around 500,000 credits this year, with its developer anticipating prices between USD 15 and USD 30 per credit depending on the destination market, including Japan, Singapore and South Korea. Those are developer expectations awaiting approval, not traded prices, and readers should treat them as an asking range rather than a market print.
The caps that shape what can leave
Export volume is not simply whatever projects generate. Under Decree 112 from 2025, as summarized by Vietnam Investment Review, credits may move overseas through bilateral agreements, United Nations mechanisms or independent standards, but transfer shares are capped to protect domestic targets. Projects in areas such as electric vehicles, charging and low emission rice may transfer up to 90 percent of credits generated, while forestry projects face a 50 percent cap.
That asymmetry will shape portfolios. A rice developer can plan around export sales for most of its volume. A forestry developer must assume half its credits stay home, where domestic exchange demand is still thin and the first surrender deadline falls in 2027.
Demand is real, but it is choosy
Buyer interest from Japan, Korea and Singapore reflects compliance and corporate needs that reward authorized credits with clear accounting. Authorization carries a premium because it reduces double counting risk. It also carries homework: registries, letters of authorization, and reporting that smaller project owners cannot easily produce alone.
The comparison, in one view
Article 6.2 offers named buyers and a December 2026 start, but volumes are unproven. Article 6.4 offers the biggest stated pipeline, above 10 million credits, with timing risk at the United Nations stage. Domestic standards offer control and a forest standard already issued, with price discovery still ahead. Forests offer a paid precedent at USD 5 per tonne under an older results-based deal. Rice offers higher hoped for prices and a program measured in hundreds of thousands of hectares, with issuance still to come.
What would confirm the pipeline is real
Watch four markers into 2027. First, whether the December 2026 bilateral projects launch on schedule. Second, how many of the 23 Article 6.4 projects complete registration. Third, whether rice credits from the Mekong program reach issuance with measurement, reporting and verification that buyers accept. Fourth, whether any authorized Vietnamese credit trades at a published price that others can benchmark.
Until then, Vietnam’s supply pipeline is best described as wide at the intake and narrow at the tap. The forests have already shown they can deliver verified tonnes and share the proceeds. The rice fields have shown they can organize at provincial scale. The Article 6 machinery now has to connect those fields and forests to buyers abroad without losing the accounting discipline that makes a credit worth buying in the first place.
Related reading
- Seven Trades and 1,310 Allowances: Vietnam’s Carbon Exchange Finds Its First Price
- The Rice Farmer’s New Harvest: Carbon Credits from the Mekong Delta
- ASEAN’s Carbon Club: Linking Exchanges Before Linking Grids?
Sources
CarbonMeld, September 2026, on the three eligible credit types, the 23 Article 6.4 projects above 10 million credits, the forest standard issued August 11, 2026 and the December 2026 bilateral project start. Vietnam Investment Review, 2026, on Decree 112 transfer caps and a low emission rice project expecting about 500,000 credits with anticipated prices of USD 15 to USD 30. Voice of Vietnam English, August 15, 2026, on government approval of the Article 6 implementation agreement with Singapore. World Bank Forest Carbon Partnership Facility reporting, 2024, on the 10.3 million tonne north central forest payment of USD 51.5 million and benefit sharing.